Smart Ways to Strengthen Your Credit Before Buying a Home
Your credit profile plays a major role in your ability to qualify for a mortgage and secure favorable loan terms. A stronger credit score can lead to better interest rates, lower monthly payments, and more loan options.

Taking the time to improve your credit before applying for a mortgage can have a lasting financial impact and make the entire homebuying process smoother.

Review Your Credit Report for Accuracy
The first step in improving your credit is understanding where you currently stand. Obtain a copy of your credit report and review it carefully for any errors or outdated information. Mistakes such as incorrect balances, duplicate accounts, or inaccurate late payments can negatively impact your score. Disputing and correcting these issues can lead to a relatively quick improvement in your credit profile.

Focus on Reducing Outstanding Debt
One of the most effective ways to improve your credit is by paying down existing debt. Lenders closely evaluate your credit utilization, which is the amount of credit you are using compared to your total available credit. Lowering your balances, especially on revolving accounts, can significantly improve your score and demonstrate responsible financial management.

Make Every Payment On Time
Payment history is one of the most important factors in your credit score. Even a single missed payment can have a negative impact. Consistently making on-time payments shows lenders that you are reliable and capable of managing debt responsibly. Setting up automatic payments or reminders can help ensure you stay on track.

Avoid Opening New Credit Accounts
Before applying for a mortgage, it is important to maintain stability in your credit profile. Opening new credit accounts can lower your average account age and may temporarily reduce your score. It can also increase your overall debt, which may impact your debt-to-income ratio. Keeping your credit activity steady during this period is key.

Give Yourself Time to See Improvement
Improving your credit does not happen overnight. Starting early gives you the opportunity to see meaningful progress before applying for a mortgage. Even small improvements can make a difference in the rates and terms you are offered, which can lead to long-term savings.

Strengthening your credit before buying a home puts you in a better position to secure the loan that fits your needs. Ready for a mortgage? Give us a call today to get started.
Home Appraisals Explained: What Buyers and Sellers Should Know

Whether you’re buying or selling, the appraisal is one of those moments that can quietly make—or break—a deal. It’s also one of the most misunderstood parts of the process.
So what actually happens during an appraisal, and how can you prepare for it? Here’s what you need to know.

What Is a Home Appraisal (and Why It Matters)?

A home appraisal is an independent estimate of a property’s market value, typically required by a lender before approving a mortgage.

In simple terms: The lender wants to make sure the home is worth what the buyer is paying.

If the appraisal comes in at (or above) the agreed price, then it’s smooth sailing. If it comes in low, that’s where things get…interesting.

1. It’s All About Comparable Sales (“Comps”)

Appraisers don’t just walk through your home and guess a number. They base value largely on recent sales of similar homes nearby, also known as “comps.”

They’ll look at things like:

  • Location and neighborhood
  • Square footage and layout
  • Condition and upgrades
  • Recent sale prices of similar properties

What this means:
Even if you feel your home is worth more, the data from your local market is what carries the most weight.

2. Condition Still Matters (More Than You Think)

While comps drive the value, the condition of your home can absolutely influence the final number. For sellers, this doesn’t mean a full renovation, it means presenting the home well.

Focus on:

  • Cleanliness and basic upkeep
  • Minor repairs (leaky faucets, chipped paint, etc.)
  • Curb appeal
  • Showing that the home is well-maintained overall

Think of it less as “upgrading” and more as removing red flags.

3. Not All Upgrades Deliver Equal Value

It’s tempting to assume every upgrade boosts your home’s appraisal, but that’s not always how it plays out.

Some improvements help more than others, especially:

  • Kitchens and bathrooms
  • Flooring and overall condition
  • Functional upgrades (like HVAC, roof, windows)

But highly personalized or luxury upgrades? They don’t always translate dollar-for-dollar in an appraisal.

Bottom line:
Renovate for market appeal—not just personal taste—if resale value is the goal.

4. A Low Appraisal Doesn’t Mean the Deal Is Dead

This is where people tend to spiral a bit. If an appraisal comes in below the purchase price, you still have options:

  • Renegotiate the price
  • Split the difference between buyer and seller
  • The buyer can bring additional cash
  • Request a reconsideration of value (with supporting comps)

It’s not ideal, but it’s also not uncommon, especially in shifting markets.

5. You Can Challenge an Appraisal (Carefully)

If something feels off, there may be an opportunity to push back, but it needs to be done strategically.

This usually involves:

  • Providing better or more relevant comparable sales
  • Highlighting overlooked upgrades or features
  • Working through your agent and lender (not directly with the appraiser)

It’s not a guaranteed fix, but in the right situation, it can make a difference.

All in all, an appraisal isn’t just a formality, it’s a key checkpoint in the transaction. Understanding how it works (and what actually influences it) can help you avoid surprises, make smarter decisions, and keep your deal moving forward.

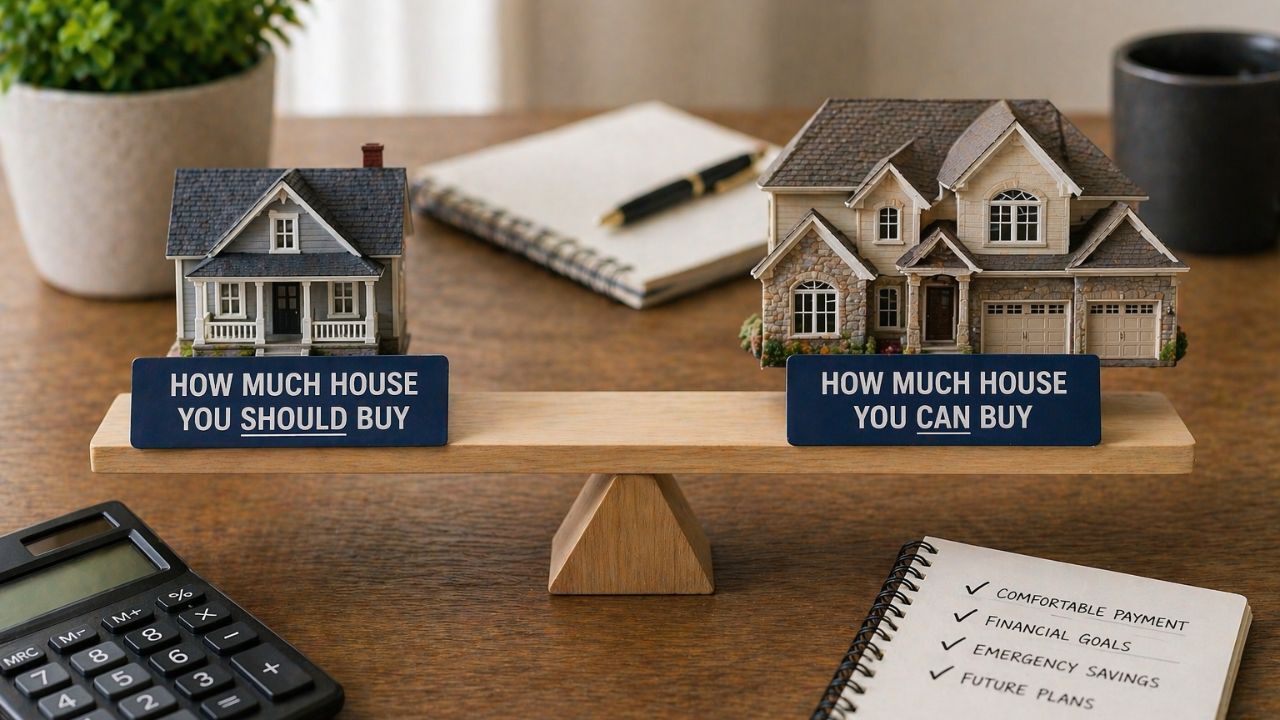
How Much House You Should Buy vs. How Much You Can Buy

One of the most common misconceptions in home buying is that the amount you are approved for is the amount you should spend. In reality, lenders calculate the maximum you qualify for based on your income, debts, and credit profile.

That number represents the upper limit of what may be acceptable from a lending perspective, not what will feel comfortable in your day-to-day life. Buying at the top of your approval range can leave very little room for flexibility, which can become stressful over time.

Your Monthly Payment Is Only Part of the Picture
Many buyers focus heavily on the mortgage payment itself, but that is only one piece of the overall cost. Property taxes, homeowners  insurance, utilities, and maintenance all contribute to your total monthly expenses. These additional costs can vary depending on the home and location, and they often increase over time. A home that seems manageable based on the mortgage alone may feel much more expensive once everything is included.

Lifestyle Should Guide Your Decision
Your home should support your lifestyle, not limit it. When you stretch your budget to the maximum, you may find yourself cutting back in other areas such as travel, savings, or everyday spending. A lifestyle first approach means choosing a home that allows you to maintain balance. This includes having room for emergencies, future goals, and the activities that matter most to you. Financial comfort plays a key role in long-term satisfaction with your home.

Planning for Future Changes
Your financial situation today may not look the same in a few years. Changes in employment, family size, or personal goals can all impact your budget. Leaving some margin between what you can afford and what you choose to spend gives you flexibility. It allows you to adapt without feeling financially strained. Buyers who plan for the future tend to make more sustainable decisions.

Peace of Mind Is a Long-Term Benefit
Owning a home should bring a sense of stability and security. When your payment fits comfortably within your budget, you are less likely to feel pressure from unexpected expenses or changes in income. This peace of mind allows you to enjoy your home rather than worry about it. In many cases, choosing a slightly less expensive home can lead to a better overall experience.

A Smarter Approach to Buying
The goal is not to buy the most expensive home you can qualify for, it is to buy the right home for your life. By focusing on affordability, lifestyle, and long-term flexibility, you can make a decision that supports both your present and your future.