How a Pending Property Tax Appeal Can Affect a Home Purchase
A seller may proudly mention that the property’s tax assessment is being challenged. That can sound like good news to a buyer hoping to keep monthly housing costs manageable. But a pending property tax appeal introduces uncertainty: the current bill may not reflect what the next owner will ultimately owe, and the appeal may not transfer with the sale.

Why Assessments and Taxes Differ

A property tax assessment is a value or classification used by a taxing authority to calculate taxes. It is not necessarily the home’s market value or the price a buyer agrees to pay. Local governments use different assessment schedules, exemptions, rates, and reassessment rules. In some places, a sale can trigger a new assessment. In others, values change according to a regular cycle. A successful appeal may lower the assessed value, but it does not guarantee a permanent reduction in the tax bill.

What Happens When an Appeal Is Pending?

A seller might have filed an appeal because the assessed value seemed too high or because the property record contained an error. The decision may arrive before closing, months afterward, or even after the next tax bill is issued. Whether the appeal continues after a sale, who receives a refund, and who is responsible for a supplemental bill depend on local law and the purchase agreement. Buyers should not assume that any expected savings belong to them.

How This Relates to Your Mortgage

Property taxes are part of the monthly housing-cost estimate lenders use when evaluating affordability. If taxes are collected through an escrow account, the lender generally bases the initial collection on available tax information and its own requirements. Future tax changes can affect the escrow portion of the payment even when the loan has a fixed interest rate. A pending appeal is therefore a budgeting issue as well as a legal or administrative one.

Documents Worth Reviewing

Ask for the most recent tax bill, the current assessment notice, and any appeal filing or decision. Find out whether the property has exemptions that may end when ownership changes. If a reduction is being advertised, ask whether it is approved or merely requested. A local tax assessor’s office can explain reassessment procedures, and a closing professional can clarify how taxes and possible refunds will be allocated between buyer and seller.

Treat a pending appeal as a question to investigate, not a promised discount. A realistic estimate of future taxes will help you decide whether the home fits your budget after closing.
Why a Shared Well Can Complicate a Mortgage Approval

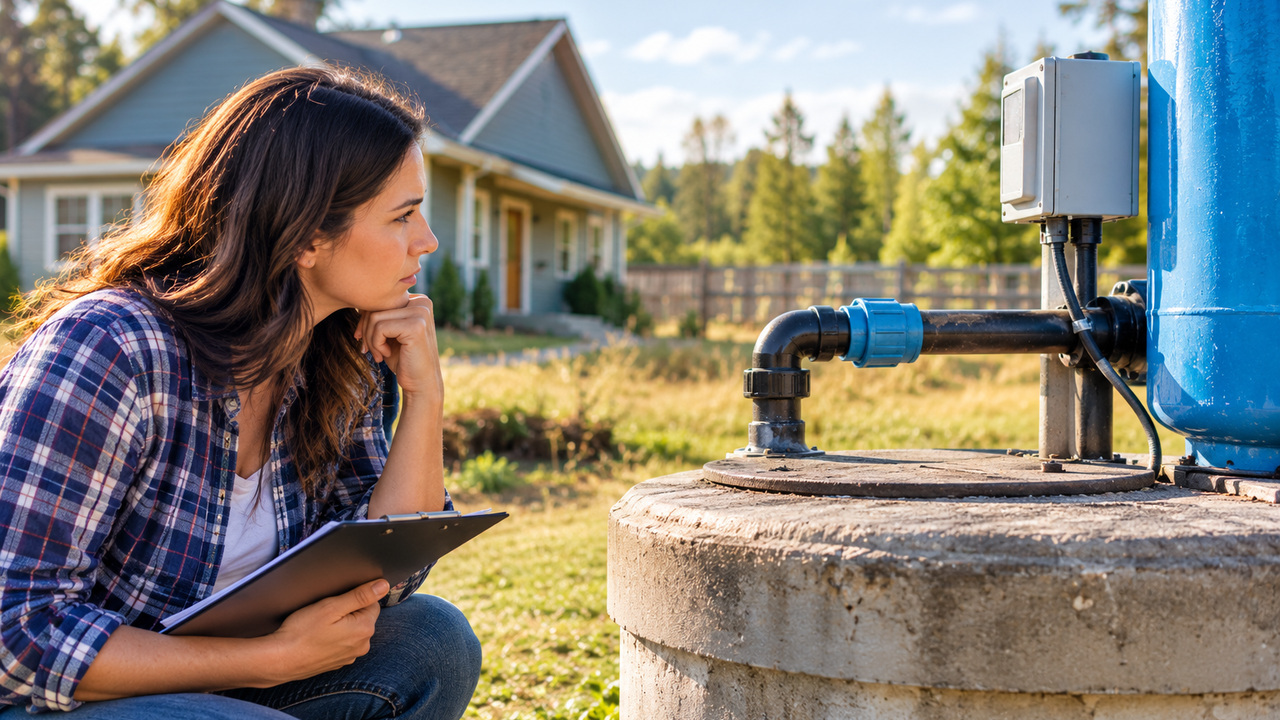
Buying a home with a private well can feel straightforward until you discover that the water source is shared with a neighboring property. Shared wells are common in some rural and semi-rural communities, but they can introduce questions that buyers of homes with municipal water may never encounter. A lender may need to understand not just whether the water works today, but whether the property has a dependable legal right to use it in the future.
A Shared Water Source Creates Shared Responsibilities

When two or more homes rely on the same well, ownership and maintenance responsibilities may be divided among the property owners. One household might have the well equipment on its land while another depends on a pipeline crossing the property line. That arrangement can work well for years, especially when neighbors cooperate. Problems can arise, however, if there is no clear agreement about repairs, electricity costs, access, or what happens when someone sells.

Lenders May Ask for Written Documentation

Depending on the loan program and property circumstances, a lender may request a recorded shared-well agreement or other documentation establishing access and responsibilities. The agreement may address who can use the well, who pays for upkeep, how repairs are approved, and whether each property can continue receiving water if ownership changes. Requirements vary, so buyers should avoid assuming that a handshake arrangement between neighbors will satisfy a lender.

Water Quality and Supply Still Matter

A shared-well agreement does not replace questions about the water itself. A lender, appraiser, or local authority may require information about water quality or whether the system can adequately serve the connected homes. Testing requirements can depend on the loan type, local rules, and property conditions. Buyers may also want to ask about the age of the pump, past interruptions, and whether the system has enough capacity during heavy use.

What to Check Before You Commit

Ask early whether the property uses a private well, a shared well, or a community water system. If it is shared, request copies of existing agreements and find out where the well and water lines are located. Ask who pays the electric bill, whether there is a maintenance fund, and how emergency repairs are handled. A title professional or real estate attorney may help clarify whether necessary access rights are documented.

It is also wise to raise the issue with your lender before the transaction is far along. Discovering a missing agreement shortly before closing can create delays while the parties gather signatures or resolve ownership questions.

A home served by a shared well is not automatically difficult to finance. The key is making sure the water supply is reliable and the arrangement is clear enough for everyone involved. A little investigation early in the buying process can prevent a surprisingly complicated issue from surfacing just as you are preparing to move.

Can You Get a Mortgage on a Home That Has Been Moved From Another Location?

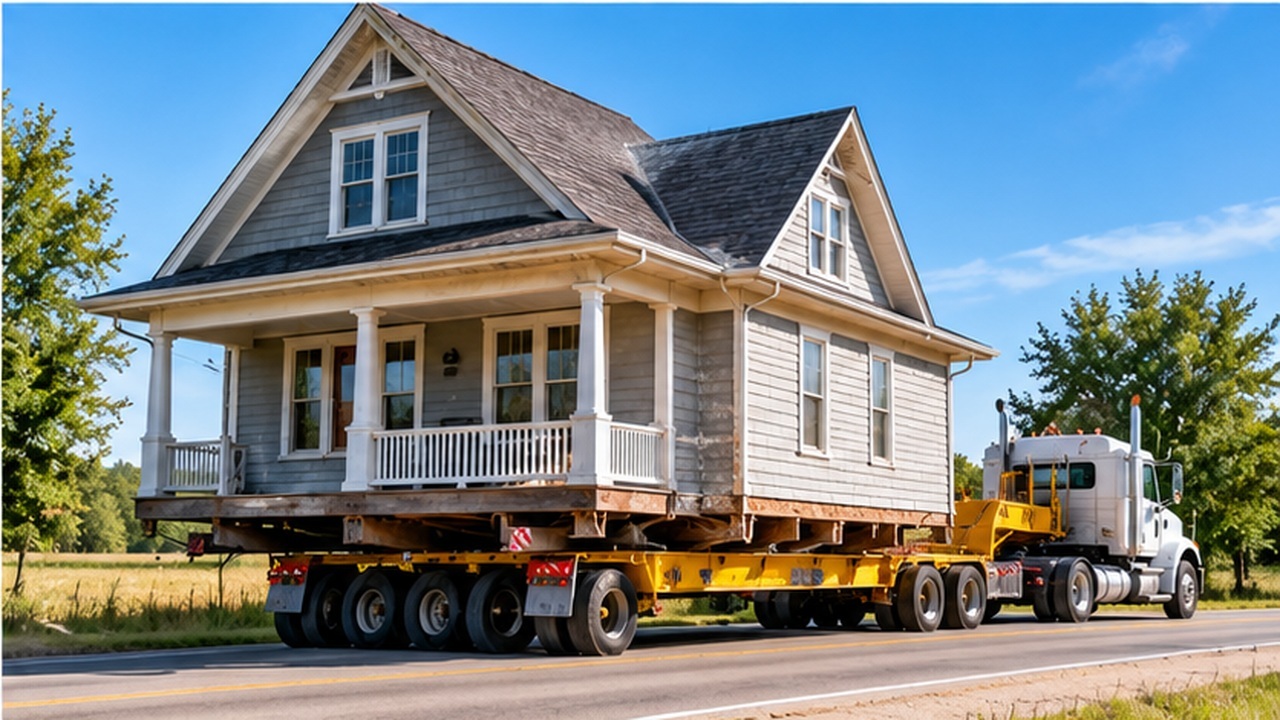
Most buyers assume that the home they are purchasing has always been located on its current property. However, some houses have been physically relocated from one location to another.

Whether a historic home was preserved by moving it or an existing structure was transported to a new lot, the property’s relocation history can create unique questions during the mortgage process.

Why Would Someone Move an Entire House?
Moving an existing home is more common than many people realize, particularly in areas where older houses are preserved or land is being redeveloped.

Instead of demolishing a structure, an owner may hire specialized contractors to lift the house, transport it, and place it on a new foundation.

In other situations, a house may be relocated to make room for construction or to preserve a building with historical significance.

Although the home may look completely normal once the project is finished, its relocation history can still be relevant when applying for financing.

The Foundation Can Be an Important Factor
When a home is moved, it generally must be placed on a suitable foundation at its new location.

Mortgage lenders and appraisers may need to evaluate whether the foundation and structure meet applicable requirements.

Depending on the property and loan program, additional documentation may be requested regarding the foundation, building permits, inspections, and completed relocation work.

Buyers should not assume that a home is automatically eligible for financing simply because it has been occupied since the move.

Property Records May Need Clarification
A relocated house may have a construction history that differs from the records associated with its current lot.

For example, the house may have been originally built decades earlier but moved to its present location much more recently.

The lender or appraiser may need to understand the difference between the original construction date and the date of relocation.

Permit records, certificates of occupancy, and other local documentation may help establish that the relocation was completed appropriately.

Missing or inconsistent information could lead to additional questions before the mortgage is approved.

Appraising a Relocated Home
Determining market value may also require careful consideration.

The appraiser evaluates the property in its current location and condition, rather than relying solely on what the structure may have been worth before it was moved.

Factors such as the foundation, overall condition, neighborhood, available comparable sales, and quality of completed work can influence the valuation.

A relocated house is not automatically worth less, but unusual property characteristics may require additional analysis.

What Buyers Should Do Before Applying
Buyers interested in a relocated home should ask when the move occurred, who performed the work, and what documentation is available.

They should also discuss the home’s history with their mortgage professional before committing to a financing timeline.

For buyers who appreciate unique or historic properties, a relocated home can offer considerable charm. The key is understanding the property’s history and confirming that its current condition and documentation support the intended mortgage financing.