Why a Home With a Private Septic System May Need Extra Mortgage Review
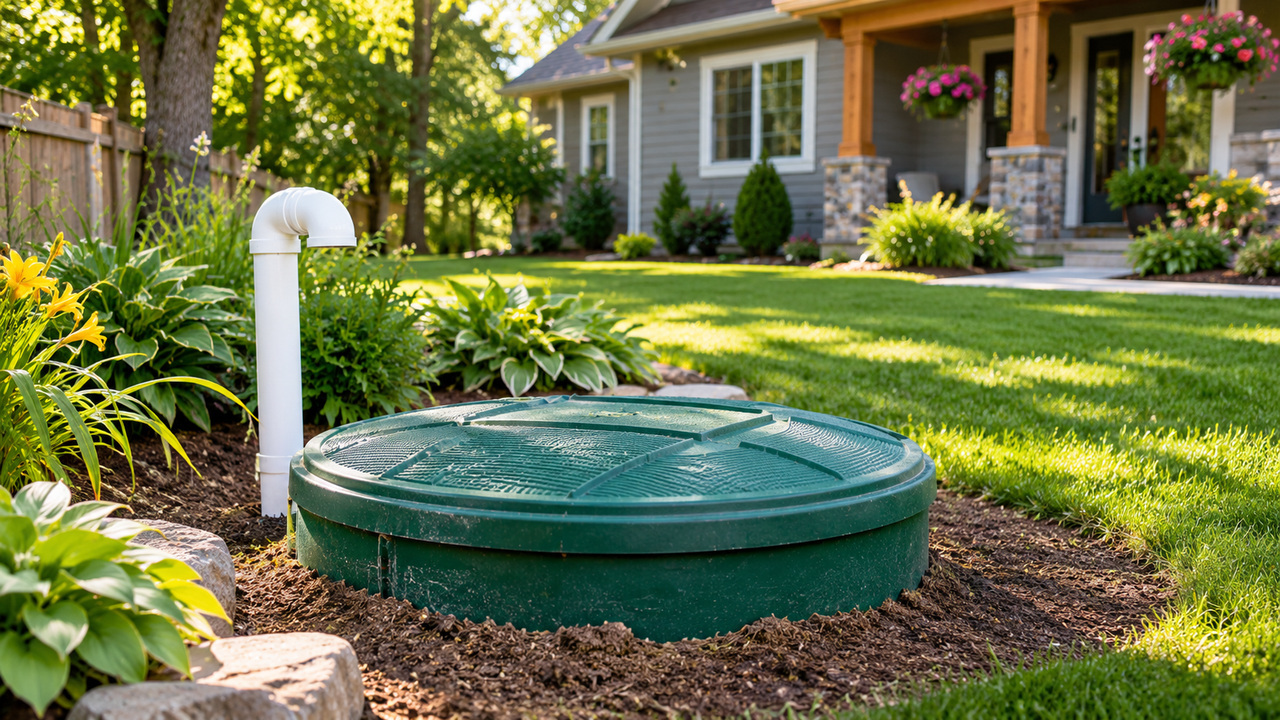
A house with a private septic system may offer the space and privacy many buyers want, especially outside areas served by public sewer lines. Yet septic systems are an important part of a property’s infrastructure, and their condition can affect both the purchase decision and the mortgage process. Buyers who understand the basics before making an offer are better prepared for inspections, documentation requests, and possible repairs.

The System Is Part of the Property

A septic system typically collects wastewater from the home, treats it in a tank, and disperses it through a drain field or another approved treatment arrangement. Unlike a public sewer connection, the homeowner is generally responsible for maintenance and repairs. Pumping schedules, household water use, soil conditions, and the age of the equipment can all influence how the system performs over time.

Why Lenders Pay Attention

Mortgage financing is secured by the property, so lenders want to know that essential systems are functional and that the home meets applicable property standards. Depending on the loan program, appraisal observations, and local regulations, a septic inspection or additional documentation may be needed. Some issues are discovered during a buyer’s independent inspection rather than the lender’s appraisal. Requirements vary, and not every home with a septic system needs the same review.

A Small Symptom Can Point to a Larger Problem

Slow drains, persistent sewage odors, wet areas near the drain field, or a history of frequent backups deserve attention. These signs do not always mean the system has failed, but they justify further investigation by a qualified professional. A replacement drain field or major system repair can be expensive and may require permits, engineering, or suitable space on the lot.

Ask About Records and Location

Before buying, request available pumping and inspection records, installation permits, and any drawings showing where the tank and drain field are located. Knowing the location matters because homeowners may be restricted from building structures, driving heavy vehicles, or planting certain trees over parts of the system. If the property has a pool, detached building, or planned addition, it is worth confirming that those improvements do not interfere with septic components.

Plan for Both Closing and Ownership

If an inspection identifies a problem, the buyer and seller may need to negotiate repairs, obtain specialist evaluations, or address a lender condition before closing. Buyers should also budget for routine pumping and eventual equipment replacement after moving in. A home warranty or standard homeowners insurance policy may not cover every septic-related expense, so review coverage carefully rather than assuming protection.

A private septic system is not a reason to reject a home automatically. Many systems operate reliably for years when properly designed and maintained. The smarter approach is to understand the system’s condition, its maintenance history, and any financing requirements before you make a long-term commitment.
Why the Source of Your Down Payment Can Matter as Much as the Amount

You have calculated your down payment and know exactly how much money you plan to bring to the purchase. That is an important step, but there is another question buyers sometimes overlook: Where is that money actually coming from?
A $40,000 down payment sitting in one savings account can create a different planning process than $40,000 being assembled from several different financial sources.

Your Down Payment May Come From Several Places
Not every buyer saves a down payment in one traditional bank account.

Funds might come from checking or savings, investments, proceeds from selling an asset, an eligible gift, or other permitted sources. Some buyers may also have money connected to a business or another type of account.

Each source can have different considerations, so knowing where the money will come from before you need it can simplify the mortgage process.

Investments May Require Planning
If part of your down payment is invested, consider what must happen before those funds become available for closing.

Selling investments may require time for transactions to settle and funds to transfer. There may also be financial or tax considerations outside the mortgage itself that you want to discuss with the appropriate professional.

The important point is not to wait until the last minute to determine how you will access the money.

Gift Funds Are Not Simply Extra Cash
Eligible gift funds can help some buyers with a home purchase, but mortgage programs can have rules regarding who may provide the gift and how it must be documented.

If someone has offered to help with your purchase, discuss the plan before money changes hands.
Knowing the requirements in advance can prevent unnecessary confusion later.

Build Your Down Payment Plan Early
Before making an offer, identify the accounts and sources you expect to use. Then ask how those funds should be handled and what documentation may be required.

This is especially useful if your down payment will come from several places rather than one established account.

Having enough money is obviously essential, but mortgage planning involves more than reaching a target dollar amount.

Understanding where your down payment will come from, how quickly the funds can become available, and what requirements apply to each source can help make the financial side of closing much more predictable.
Your down payment should not simply be a number. It should be a plan.

Why Your Mortgage Approval Can Change When the Home Has an Accessory Dwelling Unit

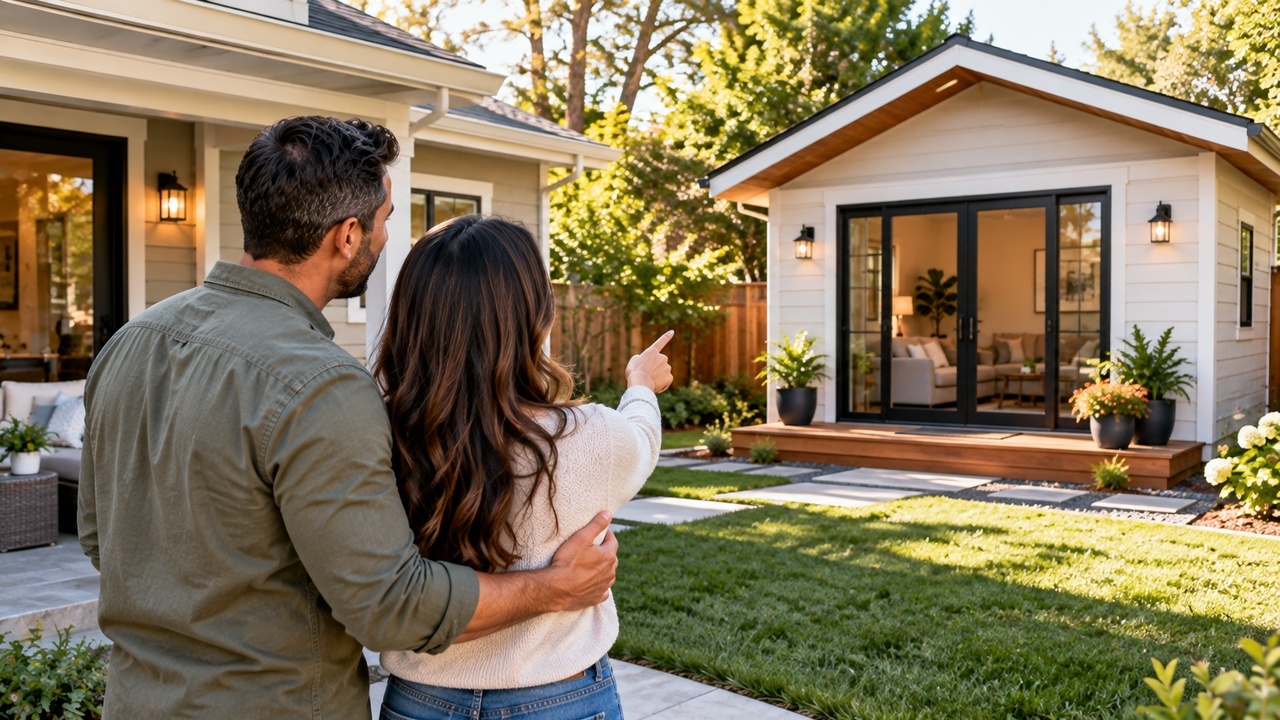
An accessory dwelling unit can make a property especially appealing. A detached guest house, converted garage, basement apartment, or backyard unit might provide space for relatives, a home office, or potential rental income.

But when you are financing the purchase, that additional living space can introduce questions that would not necessarily exist with a more traditional single-family home.

The Property Has to Be Evaluated Too
Mortgage approval is not based solely on the borrower’s income, credit, assets, and debts. The property securing the mortgage also has to meet applicable requirements.

When an ADU is present, the lender and appraiser may need to understand exactly what it is and how it relates to the primary residence.

Is it a separate structure? Does it have its own kitchen? Was an existing part of the property converted? These details can help determine how the property is evaluated.

Permits and Property Records May Matter
One important question is whether the additional living space was legally created and how it is reflected in available property records.

Buyers should not assume that a finished structure is automatically recognized as permitted living space simply because it looks professionally completed.

If something about the ADU is unclear, additional documentation or investigation may be needed.

Rental Income Is a Separate Question
Buyers sometimes see an ADU and immediately calculate how much rental income it could generate.

That potential income may be useful to your personal budget, but do not automatically assume it can be counted toward mortgage qualification.

Whether rental income from an ADU can be considered, and how much can be used, depends on the mortgage program, documentation, appraisal, occupancy plans, and other requirements.

Ask Before Building Your Budget Around It
If an ADU is an important reason you are considering a property, discuss it with your mortgage professional early. Explain how you intend to use the space and whether you are relying on anticipated rental income as part of your financial plan.

You may also want to ask your real estate professional about permits and available property information. An ADU can be an excellent feature, but it makes the property more than simply a house with an extra room.

Before assuming the additional space will strengthen your mortgage application or generate income immediately, understand how it will be treated in the transaction. That can help you evaluate the property based on what is actually possible rather than what you hope the extra space will provide.