Can a Home With an Aging Roof Still Qualify for a Mortgage?
A home with an older roof may be priced attractively, located in the perfect neighborhood, and otherwise meet everything on a buyer’s wish list. But roof condition can become an important question during mortgage approval. The issue is not simply how many birthdays the roof has had. Lenders and appraisers may be concerned about whether it protects the home adequately and whether visible defects create a property-condition problem.

Age and Condition Are Different Questions

Two roofs installed in the same year can be in very different condition. Weather exposure, materials, ventilation, installation quality, and maintenance all affect longevity. A roof that looks worn may still have useful life remaining, while a newer roof can have problems if it was installed incorrectly or damaged in a storm. Buyers should avoid assuming that age alone proves the roof needs replacement.

What an Appraiser May Notice

During the appraisal, visible signs such as missing shingles, active leaks, sagging sections, or significant deterioration may raise concerns. An appraiser is not performing the same detailed evaluation as a licensed roofing contractor, but observed issues can prompt a lender to request additional information or repairs. The exact response depends on the loan program, property condition, and lender requirements.

Why an Inspection Matters

A general home inspection can identify warning signs, but a qualified roofer may be better equipped to estimate remaining life, repair costs, and whether replacement is necessary. Buyers can ask for the roof’s approximate installation date, available warranties, permits, and records of previous repairs. If the seller says the roof was recently replaced, supporting documentation can help confirm what work was actually completed.

Insurance Can Be Another Piece of the Puzzle

Mortgage lenders commonly require acceptable homeowners insurance before closing. Some insurers may apply their own roof-age or condition standards, which can differ from mortgage requirements. A home might appear financeable but still present challenges if insurance is unavailable or unexpectedly expensive. Obtaining an insurance quote early can help buyers avoid last-minute surprises.

Possible Paths Forward

When a roof issue is identified, the parties may consider a repair before closing, a negotiated replacement, or another solution allowed by the lender and loan program. Buyers should not assume that a repair credit alone will satisfy a property-condition requirement. It is important to coordinate with the lender before agreeing to a plan, especially if work cannot be completed before the scheduled closing date.

An aging roof does not automatically prevent a home from qualifying for a mortgage. What matters is the roof’s actual condition, the applicable financing standards, and the availability of acceptable insurance. Getting reliable information early helps buyers distinguish between a manageable maintenance expense and a problem that could delay or derail the purchase.
How an Unfinished Basement Can Affect Your Mortgage Appraisal

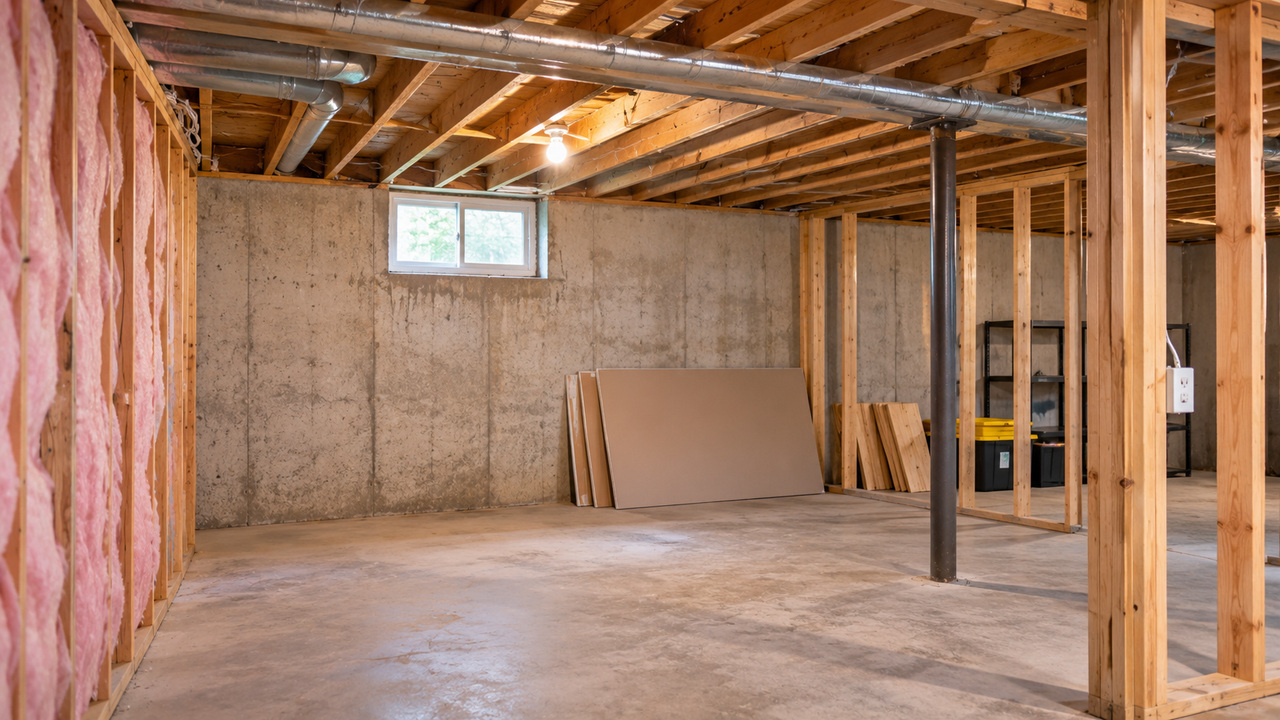
An unfinished basement can look like an opportunity. Buyers may imagine a future family room, guest space, home gym, or office. But when a home is being financed, the appraiser has to evaluate what exists today, not what the basement might become after a renovation. That distinction can affect the home’s reported living area, comparable sales, and ultimately the value used by the lender.
Finished and Unfinished Space Are Not the Same

A basement may be spacious, dry, and useful without qualifying as finished living area. Exposed framing, concrete floors, unfinished ceilings, and incomplete heating or electrical work can all affect how the space is classified. Even a beautifully finished basement may be reported separately from above-grade living area under commonly used appraisal measurement standards. Buyers should not assume that every usable square foot will be counted in the same category.

Why the Listing and Appraisal May Differ

Real estate listings sometimes describe total square footage in ways that include basement areas, while an appraisal may separate above-grade space from below-grade space. That does not necessarily mean either document is trying to mislead anyone. They may be applying different reporting conventions. The distinction matters when buyers compare a home with properties that have similar floor plans but different basement finishes.

Potential Does Not Equal Present Value

A seller may advertise an unfinished basement as space that could easily become an additional bedroom or rental suite. Those possibilities can be appealing, but they are not the same as an existing, legally permitted room. Adding bedrooms or living space may require permits, safe access, proper ceiling heights, emergency egress, and other improvements. An appraiser generally evaluates the current condition and market evidence rather than assigning full value to a project that has not been completed.

How This Can Affect Financing

A lender typically bases its loan-to-value calculation on the applicable appraised value, not simply the agreed purchase price. If the appraisal comes in below the contract price, the buyer may need to discuss options such as renegotiating, bringing additional funds, or reconsidering the purchase. An unfinished basement alone does not mean the home will appraise poorly. The outcome depends on the entire property and how comparable homes are selling.

Questions Worth Asking During a Showing

Find out whether the basement has experienced moisture intrusion, whether any past work was permitted, and which utilities are already installed. Ask for the listed square footage to be broken down between above-grade and below-grade areas. If you plan to finish the basement, obtain realistic estimates and investigate local permit requirements before treating the project as part of your financial plan.

An unfinished basement can be a valuable feature for the right buyer. Just remember that its future possibilities and its current appraised contribution are two different things. Understanding that difference helps you set a realistic budget and avoid surprises during mortgage approval.

Why a Shared Well Can Complicate a Mortgage Approval

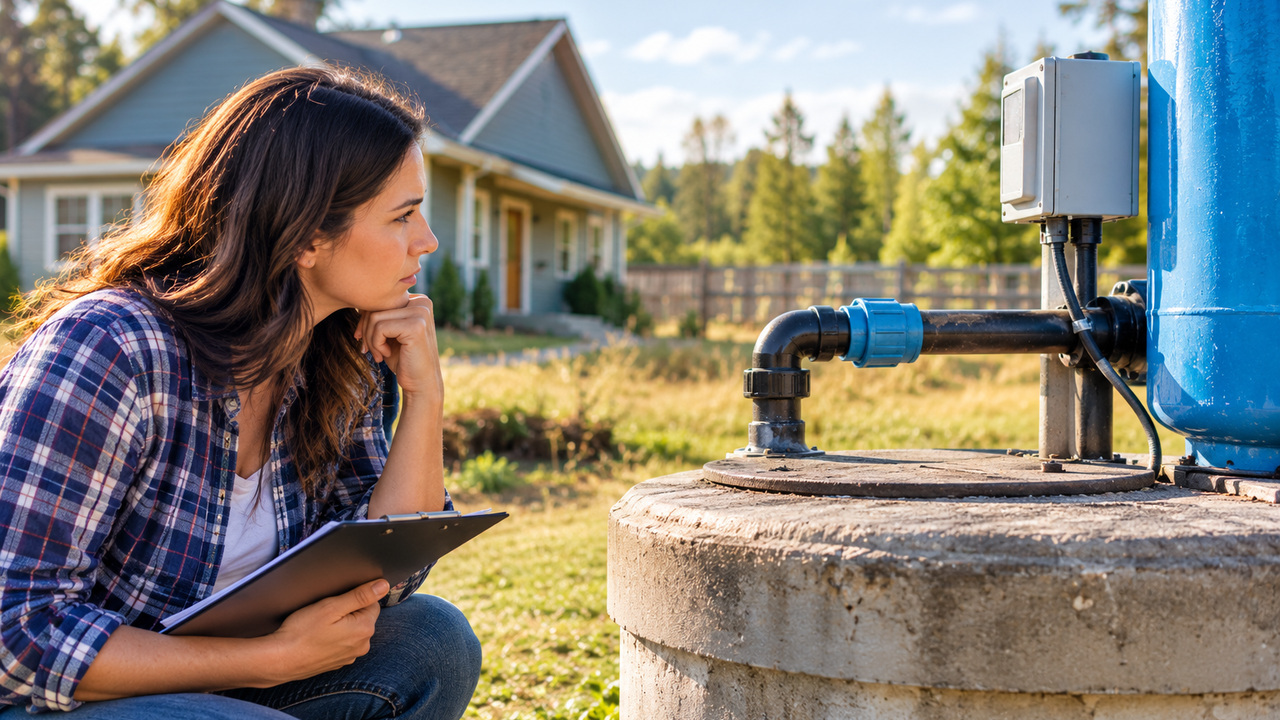
Buying a home with a private well can feel straightforward until you discover that the water source is shared with a neighboring property. Shared wells are common in some rural and semi-rural communities, but they can introduce questions that buyers of homes with municipal water may never encounter. A lender may need to understand not just whether the water works today, but whether the property has a dependable legal right to use it in the future.

A Shared Water Source Creates Shared Responsibilities

When two or more homes rely on the same well, ownership and maintenance responsibilities may be divided among the property owners. One household might have the well equipment on its land while another depends on a pipeline crossing the property line. That arrangement can work well for years, especially when neighbors cooperate. Problems can arise, however, if there is no clear agreement about repairs, electricity costs, access, or what happens when someone sells.

Lenders May Ask for Written Documentation

Depending on the loan program and property circumstances, a lender may request a recorded shared-well agreement or other documentation establishing access and responsibilities. The agreement may address who can use the well, who pays for upkeep, how repairs are approved, and whether each property can continue receiving water if ownership changes. Requirements vary, so buyers should avoid assuming that a handshake arrangement between neighbors will satisfy a lender.

Water Quality and Supply Still Matter

A shared-well agreement does not replace questions about the water itself. A lender, appraiser, or local authority may require information about water quality or whether the system can adequately serve the connected homes. Testing requirements can depend on the loan type, local rules, and property conditions. Buyers may also want to ask about the age of the pump, past interruptions, and whether the system has enough capacity during heavy use.

What to Check Before You Commit

Ask early whether the property uses a private well, a shared well, or a community water system. If it is shared, request copies of existing agreements and find out where the well and water lines are located. Ask who pays the electric bill, whether there is a maintenance fund, and how emergency repairs are handled. A title professional or real estate attorney may help clarify whether necessary access rights are documented.

It is also wise to raise the issue with your lender before the transaction is far along. Discovering a missing agreement shortly before closing can create delays while the parties gather signatures or resolve ownership questions.

A home served by a shared well is not automatically difficult to finance. The key is making sure the water supply is reliable and the arrangement is clear enough for everyone involved. A little investigation early in the buying process can prevent a surprisingly complicated issue from surfacing just as you are preparing to move.