What Happens When the Seller Has Not Paid Off a Home Improvement Loan?
A newly installed roof, upgraded windows, or modern heating system can make a home more attractive to buyers. However, what happens when the seller is still making payments on those improvements?

Depending on how the work was financed, an outstanding home improvement loan could affect the sale, the title review, and even the buyer’s mortgage closing.

Not All Home Improvement Loans Work the Same Way
Homeowners finance improvements through several methods, including personal loans, home equity loans, contractor financing, and property-assessed financing programs.

Some financing arrangements are unsecured, meaning the loan is based primarily on the borrower’s credit rather than a claim against the property.

Others may be secured by the home, creating a lien or another obligation that must be addressed during the sale.

This distinction matters because an unpaid personal loan does not necessarily interfere with transferring ownership, while a loan secured by the property may need to be resolved before closing.

Why the Title Search Matters
During the mortgage process, a title search helps identify recorded liens, ownership issues, and other claims affecting the property.

If the seller financed a renovation through a loan secured by the home, the outstanding balance may appear in the title records.

The title company and closing professionals will determine what must be paid or released to provide the title required for the transaction.

In many cases, the seller can use proceeds from the sale to pay off an outstanding secured loan. However, the payoff amount and necessary documentation must be obtained before the transaction is finalized.

Special Considerations for Property-Assessed Financing
Some energy-efficient improvements are financed through Property Assessed Clean Energy, commonly called PACE, programs.

Unlike traditional personal loans, these obligations may be collected through property tax assessments.

Depending on the program and mortgage requirements, an outstanding PACE assessment can create additional questions about lien priority, payoff obligations, and whether the financing arrangement is acceptable.

Buyers should never assume that an obligation can simply remain attached to the property without affecting their mortgage.

What Buyers Should Ask Before Closing
If a seller advertises recently completed improvements, buyers can ask whether the work has been fully paid for.

They should also find out whether any financing arrangements, warranties, or service agreements are connected to the improvements.

The goal is not to discourage buyers from purchasing homes with recent renovations. Instead, it is to make sure that the financial obligations associated with those improvements are clearly understood.

A beautiful renovation can add appeal to a property, but the paperwork behind it matters too. Addressing outstanding financing early helps protect the transaction from unexpected delays and gives buyers greater confidence about what they are purchasing.
Why a Home With a Shared Septic System Can Complicate Mortgage Financing

A home can look perfect during a showing, but certain features of the property may create questions when it comes time to secure a mortgage. One situation buyers may not anticipate is purchasing a home that shares a septic system with another property.
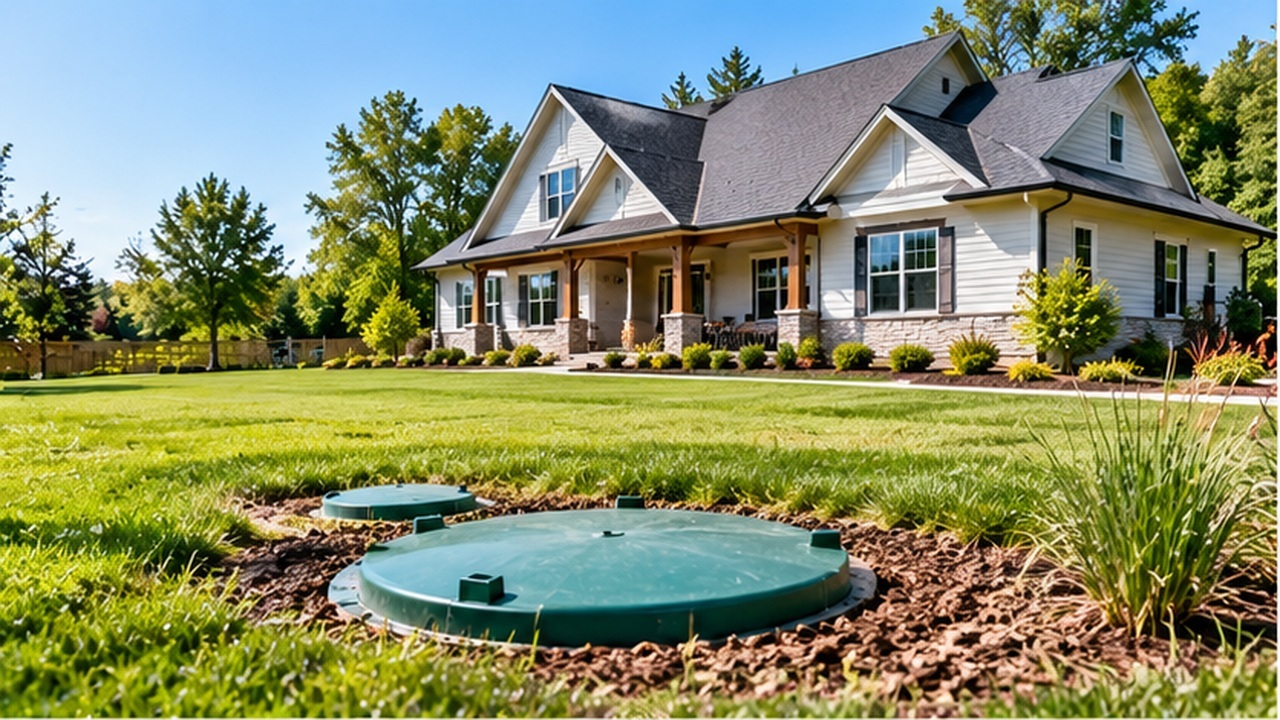
While shared systems can function effectively, they may require additional documentation and review before financing can move forward.

Understanding How a Shared Septic System Works
Most buyers are familiar with homes that connect to a public sewer system or have their own private septic tank. However, some properties share a wastewater treatment system with one or more neighboring homes.

This arrangement may have been established when the properties were originally developed or when land was divided into separate parcels. Although each home has its own plumbing, wastewater from multiple properties may flow into a common treatment system.

The important question is not simply whether the system works. Buyers also need to understand who owns it, who maintains it, and how responsibilities are divided.

Why Lenders May Request Additional Information
Mortgage lenders evaluate more than the buyer’s income and credit history. They also review the property to determine whether it meets the requirements of the loan program.

When a septic system is shared, the lender may need documentation establishing the legal right to use the system. Depending on the loan program and circumstances, this could include recorded agreements, easements, maintenance provisions, or other property records.

The lender may also need confirmation that the system meets applicable health and safety requirements.

Requirements vary by mortgage program, so buyers should not assume that every shared system will create the same financing challenges.

Who Pays When Something Goes Wrong?

A shared septic system creates an important financial question: What happens when repairs are needed?

If the tank requires pumping, a drain field fails, or the system needs replacement, the cost may be shared among participating property owners.

A written agreement can help establish how expenses are divided, who arranges maintenance, and what happens if one owner refuses to contribute.

Without clear arrangements, buyers could face unexpected disagreements or expenses after purchasing the property.

Ask Questions Before Making an Offer

Buyers considering a home with a shared septic system should request available agreements, maintenance records, inspection information, and details about participating properties.

They should also discuss the arrangement with their mortgage professional early in the process rather than waiting until underwriting begins.

A shared septic system does not automatically prevent someone from obtaining a mortgage. However, understanding the property’s legal and maintenance arrangements before making a purchase can help buyers avoid surprises, evaluate future responsibilities, and move through the financing process with greater confidence.

Why Buying a Home From a Family Member Can Make the Mortgage More Complicated

Buying a home from a parent, grandparent, sibling, or another relative may seem easier than purchasing from a stranger. You already know the seller, may know the property’s history, and might even agree on a price without extensive negotiations.

But the family relationship can introduce mortgage considerations that are different from those in a typical purchase between unrelated parties.

The Relationship Matters
A transaction between people with an existing relationship may be considered differently from a traditional arm’s-length sale.

That does not mean family transactions are prohibited. It means the lender may need to understand the relationship between the buyer and seller and review the structure of the transaction accordingly.

Being clear about the relationship from the beginning is important.

A Gift of Equity May Be Possible
One feature sometimes associated with family transactions is a gift of equity.

Instead of giving the buyer cash for a down payment, an eligible family member selling the property may be able to provide a portion of the home’s equity as a gift within applicable mortgage guidelines.

How a gift of equity can be used depends on the mortgage program and transaction, and documentation requirements can apply.

Buyers should discuss the proposed structure before agreeing on final numbers.

The Appraisal Still Matters
A family member may be willing to sell a property for less than they believe it is worth, but the agreed price does not eliminate the appraisal process when an appraisal is required.

The property still needs to be evaluated independently for the mortgage transaction.

That can become particularly important when a gift of equity or below-market sale is involved.

Treat It Like a Financial Transaction
Family relationships can make buyers and sellers more comfortable relying on verbal agreements.

A home purchase is too significant for assumptions.

Make sure the purchase price, credits, responsibilities, timelines, and other terms are properly documented through the appropriate transaction paperwork.

Buying a relative’s home can create an opportunity that would never reach the open market. It can also allow a property with family history to remain within the family.

The key is to remember that familiarity between buyer and seller does not eliminate the mortgage process.

Discuss the family relationship, proposed purchase price, and any planned gift of equity with your mortgage and real estate professionals early so the transaction can be structured correctly from the beginning.