What Happens to Your Mortgage Options When a Home Does Not Appraise as Expected?
You have negotiated a purchase price, your offer has been accepted, and the mortgage process is moving forward. Then the appraisal comes back lower than expected. For buyers, that can be unsettling, but a low appraisal does not automatically mean the purchase is over. What happens next depends on the contract, available funds, financing, and what the buyer and seller are willing to do.

Why the Appraised Value Matters to Your Mortgage
Mortgage financing is generally based in part on the property’s appraised value. If a buyer agrees to pay $425,000 but the home appraises for $400,000, the lender does not simply treat the property as though it were worth the higher amount.

This can change the loan-to-value calculation and potentially affect how much the buyer can borrow under the planned financing structure. That is when the buyer may need to evaluate several possible paths forward.

The Purchase Price May Be Renegotiated
One possibility is negotiating with the seller to reduce the purchase price. A seller is not necessarily required to lower the price simply because of the appraisal, but the appraisal can provide new information for both sides of the transaction. Depending on the market, contract, and circumstances, the parties may agree to a different price.

The Buyer May Contribute Additional Cash
Another possibility is for the buyer to cover some or all of the difference between the purchase price and the value being used for financing. That does not necessarily mean paying the entire appraisal gap dollar for dollar. The amount needed depends on the loan structure, down payment, and any changes made to the transaction.

Before contributing additional cash, buyers should consider what doing so would leave available for closing costs, reserves, moving expenses, and expenses after purchasing the home.

The Financing Structure May Be Revisited
Sometimes the mortgage strategy itself can be adjusted. A mortgage professional may be able to evaluate whether changing the down payment, loan amount, or another component of the financing creates a workable alternative. Available options will depend on the buyer’s finances and the loan program.

In certain circumstances, there may also be a process for questioning or reconsidering an appraisal when credible information supports doing so.

Know Your Options Before Making a Decision
A low appraisal can create an unexpected decision point, but buyers should avoid assuming there is only one solution. The purchase price, additional cash, financing structure, appraisal findings, and terms of the purchase contract can all influence what happens next.

Understanding those options can help buyers make a financial decision based on the complete picture rather than reacting to one number on an appraisal report.
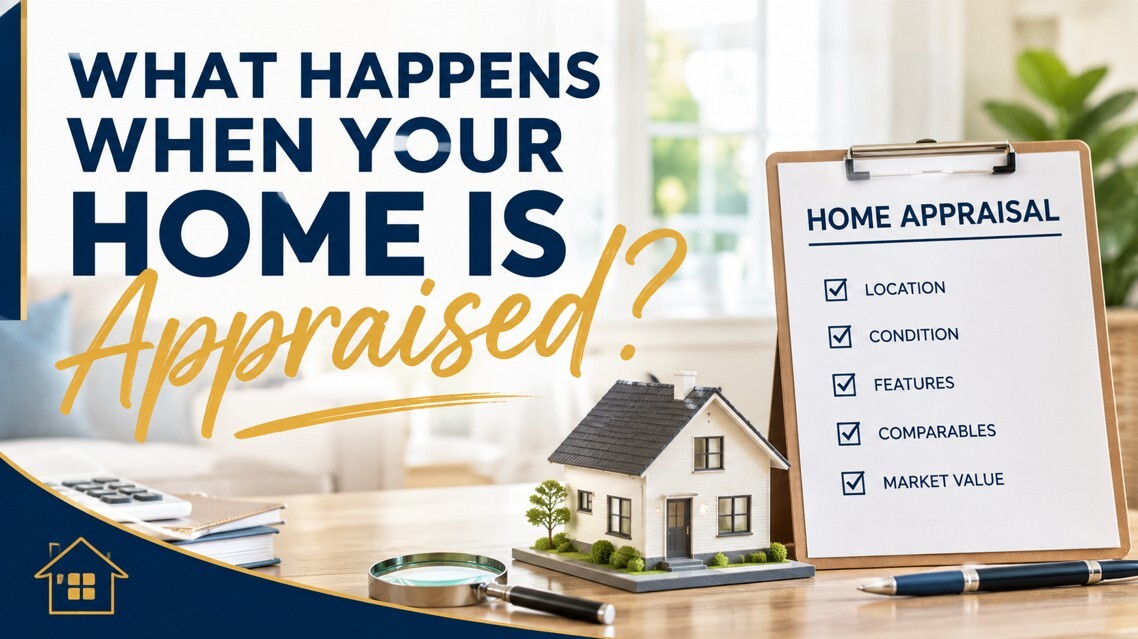
What Happens When Your Home Is Appraised?

Buying a home involves several important steps, and one of the most significant is the appraisal. While buyers often focus on inspections, financing, and closing dates, the appraisal plays a key role in the mortgage process. Understanding what happens during an appraisal and why it matters can help you feel more confident as you move toward homeownership.
What Is a Home Appraisal?

A home appraisal is an independent professional opinion of a property’s market value. Your lender orders the appraisal to help confirm that the home’s value supports the amount being borrowed. The appraiser is a neutral third party whose job is to evaluate the property’s condition, features, location, and recent sales of similar homes in the area.

What the Appraiser Looks For

During the visit, the appraiser evaluates both the interior and exterior of the home. They consider the home’s size, floor plan, condition, upgrades, lot size, and overall appeal. They also compare the property to recently sold homes with similar characteristics to determine a fair market value.

What Happens After the Appraisal?

Once the appraisal is complete, the lender reviews the report. If the appraised value meets or exceeds the purchase price, the loan process usually continues as planned. If the appraisal comes in lower than the agreed purchase price, your real estate agent and mortgage professional will discuss the available options. Depending on the situation, the buyer and seller may renegotiate the price, the buyer may choose to contribute additional funds, or other solutions may be explored.

Why the Appraisal Protects Everyone

Although buyers sometimes worry about the appraisal, it serves an important purpose. It helps ensure that both the buyer and lender are making a sound financial investment based on the property’s market value. This added layer of protection benefits everyone involved in the transaction.

An appraisal is not simply another item to check off your closing checklist. It is an important step that helps confirm the value of one of the biggest investments you will ever make. Understanding how the process works allows you to move through your home purchase with greater confidence and fewer surprises.

The Key Details About Home Appraisals That You Might Not Know

A home appraisal is a critical step in the buying, selling, or refinancing process, yet many people don’t fully understand how it works or what factors influence it. Whether you’re a buyer, seller, or homeowner looking to refinance, here are some key details about home appraisals that you might not know.

1. Appraisals Are Different from Home Inspections

Many people confuse appraisals with home inspections. While both assess the condition of a home, an appraisal determines the home’s fair market value, whereas an inspection focuses on identifying potential issues or necessary repairs. Lenders require appraisals to ensure the loan amount aligns with the property’s worth.

2. Appraisers Use a Comparable Sales Approach

To determine a home’s value, appraisers analyze recent sales of similar homes in the area (comps). Factors like square footage, location, upgrades, and market trends play a role. If there aren’t enough comparable sales, the appraisal may be based on a cost or income approach instead.

3. A Low Appraisal Can Impact Your Loan

If an appraisal comes in lower than the agreed purchase price, buyers may have to renegotiate with the seller, pay the difference out of pocket, or walk away from the deal. For refinancing, a low appraisal can mean you won’t qualify for the loan amount you need.

4. Homeowners Can Boost Their Appraisal Value

Small improvements, such as fresh paint, minor repairs, and enhanced curb appeal, can positively impact an appraisal. While appraisers focus on objective factors, a well-maintained home with modern upgrades can make a difference in perceived value.

5. You Can Challenge an Appraisal

If you believe an appraisal is inaccurate, you can dispute it. Providing additional comparable sales data or pointing out overlooked features can sometimes lead to a revised valuation. However, the process requires solid evidence and lender approval.

6. Market Conditions Influence Appraisals

Appraisals are affected by local market trends. In a seller’s market, rising home prices can lead to appraisal gaps, while in a buyer’s market, lower demand may result in more conservative valuations. Staying informed about market conditions can help set realistic expectations.

Understanding the Appraisal Process

Home appraisals play a crucial role in real estate transactions. Whether buying, selling, or refinancing, knowing how appraisals work can help you navigate the process more effectively and avoid surprises.