
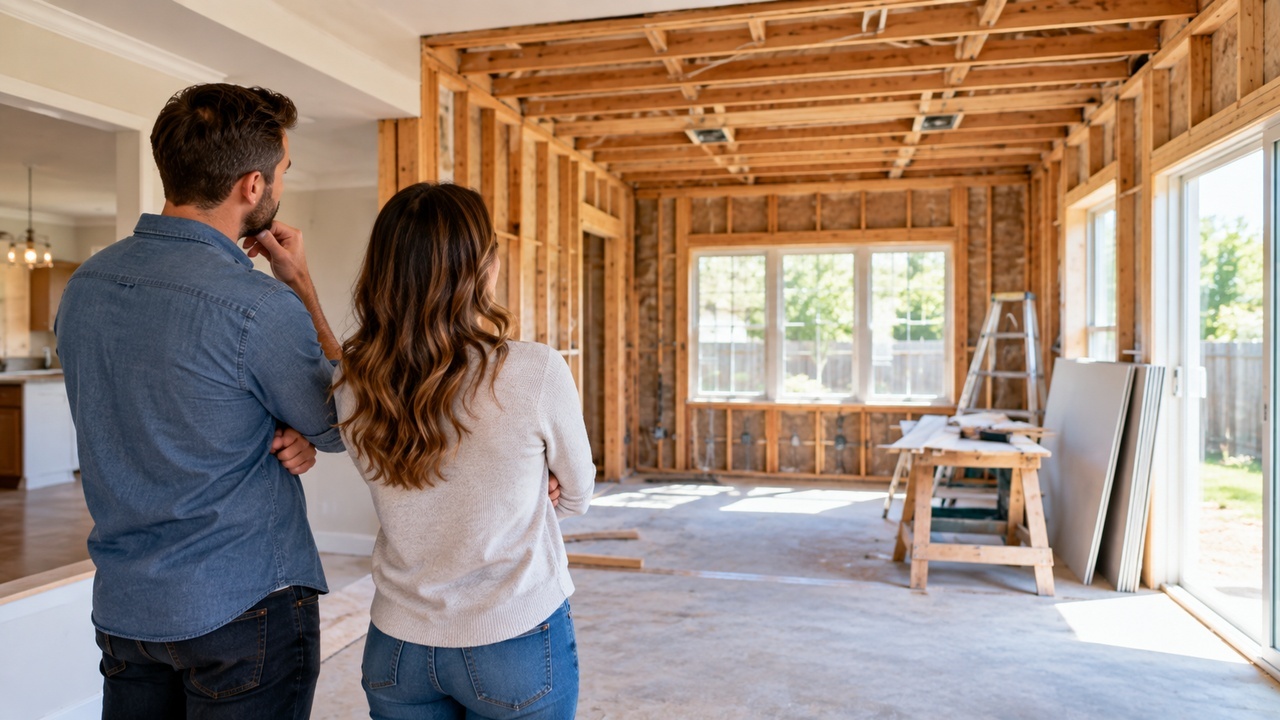
 You find a home you love, but there is one unusual feature. Maybe the previous owner started adding a bedroom and never finished it. Perhaps a bathroom is partially remodeled, a garage conversion is incomplete, or a new section of the house is still visibly under construction.
Buyers may see opportunity in unfinished space, but a mortgage lender may need to evaluate the property as it exists today.
Financing Is Based on the Current Property
It is easy to walk through an unfinished addition and imagine what it could become.
The mortgage transaction, however, generally has to consider the property’s current condition rather than simply the buyer’s plans for completing it later.
The appraiser may need to identify unfinished areas and determine how they affect the property being valued.
Not All Unfinished Projects Are Equal
Missing cosmetic finishes are different from major incomplete construction.
A room awaiting paint or updated flooring presents a different situation than an addition with exposed framing, unfinished electrical work, missing plumbing fixtures, or other incomplete components.
The extent and type of unfinished work can influence what questions need to be answered.
Permits Can Become Part of the Conversation
An addition also raises another important question: Was the work properly permitted when required?
Buyers should understand what was added, who performed the work, and what information is available through the seller or applicable local records.
An attractive partially completed space should not automatically be assumed to be recognized living area.
Do Not Assume You Can Finish It After Closing
Buyers sometimes approach an unfinished project with a simple plan: purchase the property now and complete everything later.
That may ultimately be possible, but it should not be assumed before the financing has been reviewed.
Depending on the property condition and mortgage program, incomplete work could require additional evaluation or affect available financing options.
If you are seriously considering a home with an unfinished addition, show the details to your mortgage professional as early as possible. Photos, listing information, disclosures, and information about the work can help start the conversation.
A half-finished room may look like an opportunity to create exactly what you want.
Just remember that before you can finish the project as the homeowner, you first have to successfully purchase the property in its present condition.
