Why the Source of Your Down Payment Can Matter as Much as the Amount
You have calculated your down payment and know exactly how much money you plan to bring to the purchase. That is an important step, but there is another question buyers sometimes overlook: Where is that money actually coming from?

A $40,000 down payment sitting in one savings account can create a different planning process than $40,000 being assembled from several different financial sources.

Your Down Payment May Come From Several Places
Not every buyer saves a down payment in one traditional bank account.

Funds might come from checking or savings, investments, proceeds from selling an asset, an eligible gift, or other permitted sources. Some buyers may also have money connected to a business or another type of account.

Each source can have different considerations, so knowing where the money will come from before you need it can simplify the mortgage process.

Investments May Require Planning
If part of your down payment is invested, consider what must happen before those funds become available for closing.

Selling investments may require time for transactions to settle and funds to transfer. There may also be financial or tax considerations outside the mortgage itself that you want to discuss with the appropriate professional.

The important point is not to wait until the last minute to determine how you will access the money.

Gift Funds Are Not Simply Extra Cash
Eligible gift funds can help some buyers with a home purchase, but mortgage programs can have rules regarding who may provide the gift and how it must be documented.

If someone has offered to help with your purchase, discuss the plan before money changes hands.
Knowing the requirements in advance can prevent unnecessary confusion later.

Build Your Down Payment Plan Early
Before making an offer, identify the accounts and sources you expect to use. Then ask how those funds should be handled and what documentation may be required.

This is especially useful if your down payment will come from several places rather than one established account.

Having enough money is obviously essential, but mortgage planning involves more than reaching a target dollar amount.

Understanding where your down payment will come from, how quickly the funds can become available, and what requirements apply to each source can help make the financial side of closing much more predictable.
Your down payment should not simply be a number. It should be a plan.
Why Your Mortgage Approval Can Change When the Home Has an Accessory Dwelling Unit

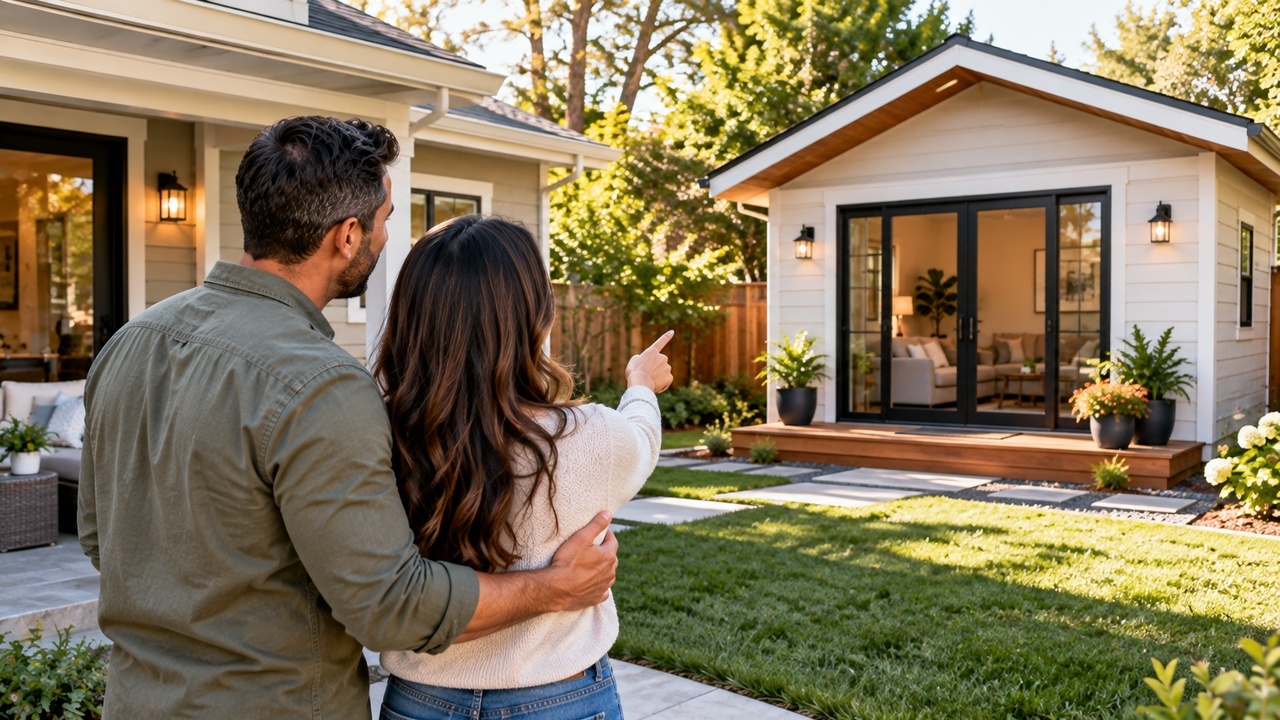
An accessory dwelling unit can make a property especially appealing. A detached guest house, converted garage, basement apartment, or backyard unit might provide space for relatives, a home office, or potential rental income.
But when you are financing the purchase, that additional living space can introduce questions that would not necessarily exist with a more traditional single-family home.

The Property Has to Be Evaluated Too
Mortgage approval is not based solely on the borrower’s income, credit, assets, and debts. The property securing the mortgage also has to meet applicable requirements.

When an ADU is present, the lender and appraiser may need to understand exactly what it is and how it relates to the primary residence.

Is it a separate structure? Does it have its own kitchen? Was an existing part of the property converted? These details can help determine how the property is evaluated.

Permits and Property Records May Matter
One important question is whether the additional living space was legally created and how it is reflected in available property records.

Buyers should not assume that a finished structure is automatically recognized as permitted living space simply because it looks professionally completed.

If something about the ADU is unclear, additional documentation or investigation may be needed.

Rental Income Is a Separate Question
Buyers sometimes see an ADU and immediately calculate how much rental income it could generate.

That potential income may be useful to your personal budget, but do not automatically assume it can be counted toward mortgage qualification.

Whether rental income from an ADU can be considered, and how much can be used, depends on the mortgage program, documentation, appraisal, occupancy plans, and other requirements.

Ask Before Building Your Budget Around It
If an ADU is an important reason you are considering a property, discuss it with your mortgage professional early. Explain how you intend to use the space and whether you are relying on anticipated rental income as part of your financial plan.

You may also want to ask your real estate professional about permits and available property information. An ADU can be an excellent feature, but it makes the property more than simply a house with an extra room.

Before assuming the additional space will strengthen your mortgage application or generate income immediately, understand how it will be treated in the transaction. That can help you evaluate the property based on what is actually possible rather than what you hope the extra space will provide.

Why Changing Jobs for More Money Can Still Complicate a Home Purchase

Getting a new job with a higher salary sounds like good financial news, especially when you are preparing to buy a home. But if the change happens while you are applying for a mortgage, the timing can create additional questions. Mortgage qualification is not based solely on how much you earn. Lenders also evaluate the stability, history, and documentation of the income being used to qualify.

Higher Income Does Not Automatically Mean Easier Approval
A substantial raise can strengthen a buyer’s finances, but a new employment situation may need to be reviewed before that additional income can be used.

The type of compensation matters.

Moving from one salaried position to another may be relatively straightforward in some circumstances.

Changing from salary to commission, becoming self-employed, accepting variable hours, or moving into another compensation structure can require a different evaluation.

That distinction can matter even when the new position has greater earning potential.

Timing Can Create Extra Documentation
Employment and income are typically verified during the mortgage process.

If you change jobs after applying, the information originally provided on your application may no longer reflect your current employment.

Additional documentation may be required. Depending on the situation, that could include an offer letter, updated employment verification, or evidence that the new job has started.

Requirements vary based on the loan and circumstances.

A Career Change Can Be Different From a Job Change
Not all employment changes are viewed exactly the same way.

Moving to another employer while continuing similar work can present a different income history than changing industries, switching compensation structures, or starting your own business.

That does not mean buyers cannot make career moves while purchasing a home. It means the effect should be understood before making the change.

Talk Before You Give Notice
One of the simplest ways to avoid an unexpected mortgage complication is to communicate before changing employment.

If you are under contract or actively applying for financing, discuss the potential change with your mortgage professional before resigning from your current position.

Provide the details of the new job, including the anticipated start date and how you will be paid.

A better-paying opportunity can be an excellent career decision. The goal is not to avoid advancement simply because you are buying a house. It is to understand how the timing and structure of the change could affect your financing so that a positive career move does not create an unexpected problem before closing.