How Your Mortgage Fits Into Your Overall Financial Plan
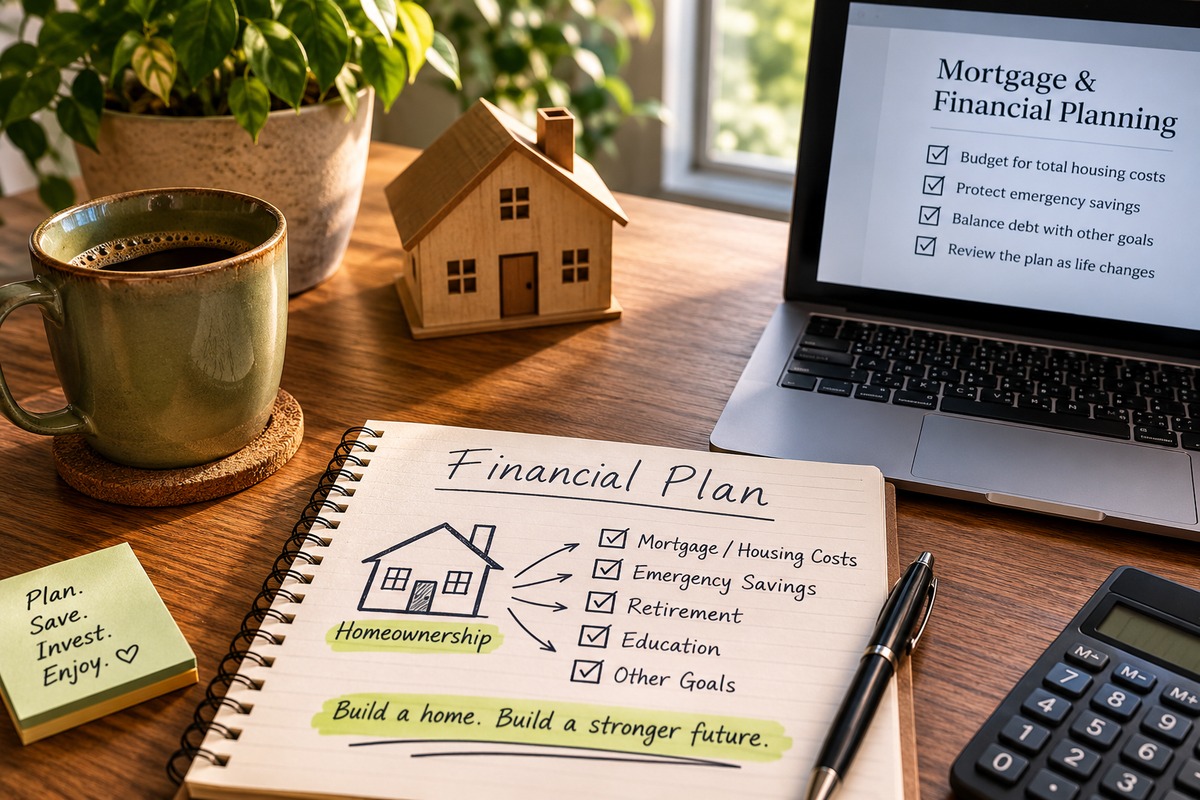
A mortgage is often the largest financial commitment a household carries, but it should not be viewed separately from the rest of your financial life. Your housing payment affects how much you can save, invest, spend, and prepare for future goals. Understanding how your mortgage fits into your overall plan can help you make decisions that support both homeownership and long-term financial stability.

Start With the Complete Housing Cost

Your mortgage payment may include principal, interest, property taxes, homeowners insurance, and possibly mortgage insurance or homeowners association dues. Maintenance, utilities, and repairs also belong in the housing budget. Looking at the complete cost provides a more accurate picture than focusing only on principal and interest.

Protect Your Emergency Savings

Homeownership creates responsibilities that can arrive without warning. A repair fund and general emergency savings can help you manage unexpected expenses without relying heavily on credit. Your mortgage strategy should leave room to build and maintain those reserves after closing.

Balance Debt With Other Goals

Paying extra toward your mortgage may reduce interest and shorten the loan term, but it is important to consider other priorities. Retirement contributions, education savings, insurance coverage, and higher-interest debt may also require attention. The best approach depends on your complete financial picture rather than one goal alone.

Review the Plan as Life Changes

Income, family needs, career plans, and financial priorities change over time. Reviewing your mortgage regularly can help you decide whether your current payment, loan term, and home still support your goals. A mortgage professional and financial advisor can help you evaluate options when major changes occur.

Your mortgage should support your financial plan, not prevent you from pursuing it. By budgeting for the complete cost of ownership, protecting savings, balancing competing goals, and reviewing your strategy over time, you can make homeownership a stable part of your broader financial future.
Why Annual Mortgage Checkups Are a Smart Financial Habit

Your mortgage is one of the largest financial commitments you will ever make, yet many homeowners rarely review it after closing. Just as annual physicals help you stay healthy, an annual mortgage checkup can help ensure your loan, insurance, taxes, and financial goals remain aligned. Spending a few minutes reviewing your mortgage each year can uncover opportunities to save money and avoid costly surprises.
Review Your Interest Rate
Mortgage rates change over time, and so do your financial goals. While refinancing is not the right choice for everyone, reviewing current market conditions can help you determine whether opportunities exist to lower your monthly payment, shorten your loan term, or access equity responsibly.

Check Your Escrow Account
Property taxes and homeowners insurance premiums often change from year to year. Reviewing your escrow statement helps you understand why your monthly payment may have increased or decreased and gives you time to prepare for adjustments before they affect your budget.

Evaluate Your Home Equity
As you make mortgage payments and home values change, your equity grows. Understanding how much equity you have can help you plan for future renovations, debt consolidation, or other financial goals. It also allows you to track the progress you are making toward full ownership.

Update Your Financial Goals
Life changes quickly. A new job, growing family, retirement planning, or paying off other debt may influence how your mortgage fits into your overall financial picture. An annual review is a good opportunity to make sure your home financing continues to support your long-term goals.

A mortgage should not be something you think about only when you buy or sell a home. A simple yearly review helps you stay informed, identify opportunities, and make confident financial decisions throughout your homeownership journey.

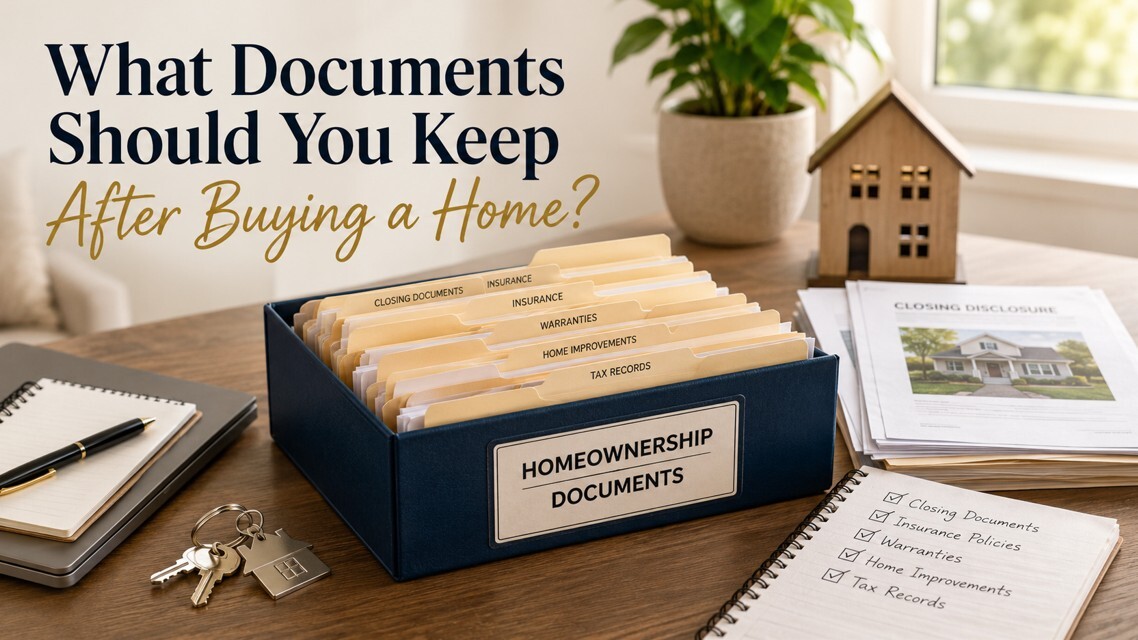
What Documents Should You Keep After Buying a Home?

Buying a home comes with a significant amount of paperwork, and once the excitement of closing day has passed, it can be tempting to file everything away without another thought. However, keeping the right documents organized can save time, reduce stress, and protect your investment if questions or unexpected situations arise in the future.

Keep Your Closing Documents
Your closing package contains important records that document the purchase of your home. This includes the Closing Disclosure, settlement statement, promissory note, deed, and mortgage documents. These records provide proof of ownership, outline the terms of your loan, and may be needed if you refinance, sell your home, or resolve a title issue.

Save Insurance and Warranty Information
Keep copies of your homeowners insurance policy and any updates or renewal notices. If your home came with builder warranties, appliance warranties, or a home warranty plan, store those documents together in an easily accessible location. Having these records available can make filing claims much easier.

Organize Home Improvement Records
Any major repairs, renovations, or upgrades should be documented with receipts, contracts, permits, and before-and-after photos. These records may help support insurance claims, provide documentation for future buyers, and potentially reduce taxable gains when you eventually sell your home.

Store Everything Securely
Many homeowners choose to keep digital copies in a secure cloud storage service while also maintaining physical copies of essential documents in a fireproof safe. Having both versions ensures your records remain available if something happens to the originals.

A little organization today can prevent frustration years from now. By keeping your most important homeownership documents together and updated, you will be better prepared for refinancing, insurance claims, tax questions, and eventually selling your home.