CALL TODAY: 818-707-4131  • Company NMLS 1777223 • Company DRE: 02075839

Blog

What’s Ahead For Mortgage Rates This Week – November 9th, 2026
With a relatively light week for economic releases, the primary focus of the economic landscape is the nonfarm payroll report, which has shown a positive trend over the last few releases. This should help consumers keep up with current inflation levels, although the Federal Reserve has remained firm in its commitment to reaching its 2% inflation target.

The unemployment rate has also continued to trend downward after reaching a high of 4.5% last year. The economy continues to be reported as healthy, but with ongoing geopolitical conflicts and other uncertainties, inflation remains a major concern for many. The likelihood of the Federal Reserve maintaining current interest rates remains high.

Unemployment Rate
The US unemployment rate dropped to 4.2% in June 2026, down from 4.3% in May and below expectations, as many people left the workforce. The number of unemployed individuals fell by 213,000 to 7.09 million, while total employment declined by 507,000 to 162.26 million. The labor force contracted by 720,000 to 169.36 million, with the participation rate falling to 61.5%, its lowest level since March 2021. The employment-population ratio also dipped to a four-year low of 59.0%. The broader U-6 unemployment rate, which includes discouraged and underemployed workers, decreased to 7.9% from 8.1%.

Nonfarm Payroll
The US economy added 57K jobs in June 2026, well below the downwardly revised 129K in May and forecasts of 110K. This was the lowest monthly job gain in four months, but it was still roughly in line with the average monthly change over the prior 12 months (+36K). In June, employment continued to trend upward in professional and business services, social assistance, and health care. Employment in leisure and hospitality declined.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw a decrease of -0.03%, bringing the current rate to 6.57%.
  • 30-Year FRM rates saw a decrease of -0.06%, bringing the current rate to 7.18%.

MND Rate Index

  • 30-Year FHA rates saw a decrease of -0.08%, with the current rate at 6.82%.
  • 30-Year VA rates saw a decrease of -0.07%, with the current rate at 6.84%.

Jobless Claims
Initial jobless claims came in at 194,000, compared to the expected 200,000. The previous week’s figure was 200,000.

What’s Ahead
The week ahead is expected to be relatively light, with the Federal Reserve scheduled to announce its interest rate decision midweek.
Can a Home With an Aging Roof Still Qualify for a Mortgage?

A home with an older roof may be priced attractively, located in the perfect neighborhood, and otherwise meet everything on a buyer’s wish list. But roof condition can become an important question during mortgage approval. The issue is not simply how many birthdays the roof has had. Lenders and appraisers may be concerned about whether it protects the home adequately and whether visible defects create a property-condition problem.
Age and Condition Are Different Questions

Two roofs installed in the same year can be in very different condition. Weather exposure, materials, ventilation, installation quality, and maintenance all affect longevity. A roof that looks worn may still have useful life remaining, while a newer roof can have problems if it was installed incorrectly or damaged in a storm. Buyers should avoid assuming that age alone proves the roof needs replacement.

What an Appraiser May Notice

During the appraisal, visible signs such as missing shingles, active leaks, sagging sections, or significant deterioration may raise concerns. An appraiser is not performing the same detailed evaluation as a licensed roofing contractor, but observed issues can prompt a lender to request additional information or repairs. The exact response depends on the loan program, property condition, and lender requirements.

Why an Inspection Matters

A general home inspection can identify warning signs, but a qualified roofer may be better equipped to estimate remaining life, repair costs, and whether replacement is necessary. Buyers can ask for the roof’s approximate installation date, available warranties, permits, and records of previous repairs. If the seller says the roof was recently replaced, supporting documentation can help confirm what work was actually completed.

Insurance Can Be Another Piece of the Puzzle

Mortgage lenders commonly require acceptable homeowners insurance before closing. Some insurers may apply their own roof-age or condition standards, which can differ from mortgage requirements. A home might appear financeable but still present challenges if insurance is unavailable or unexpectedly expensive. Obtaining an insurance quote early can help buyers avoid last-minute surprises.

Possible Paths Forward

When a roof issue is identified, the parties may consider a repair before closing, a negotiated replacement, or another solution allowed by the lender and loan program. Buyers should not assume that a repair credit alone will satisfy a property-condition requirement. It is important to coordinate with the lender before agreeing to a plan, especially if work cannot be completed before the scheduled closing date.

An aging roof does not automatically prevent a home from qualifying for a mortgage. What matters is the roof’s actual condition, the applicable financing standards, and the availability of acceptable insurance. Getting reliable information early helps buyers distinguish between a manageable maintenance expense and a problem that could delay or derail the purchase.

Why a Home With a Private Septic System May Need Extra Mortgage Review

A house with a private septic system may offer the space and privacy many buyers want, especially outside areas served by public sewer lines. Yet septic systems are an important part of a property’s infrastructure, and their condition can affect both the purchase decision and the mortgage process. Buyers who understand the basics before making an offer are better prepared for inspections, documentation requests, and possible repairs.

The System Is Part of the Property

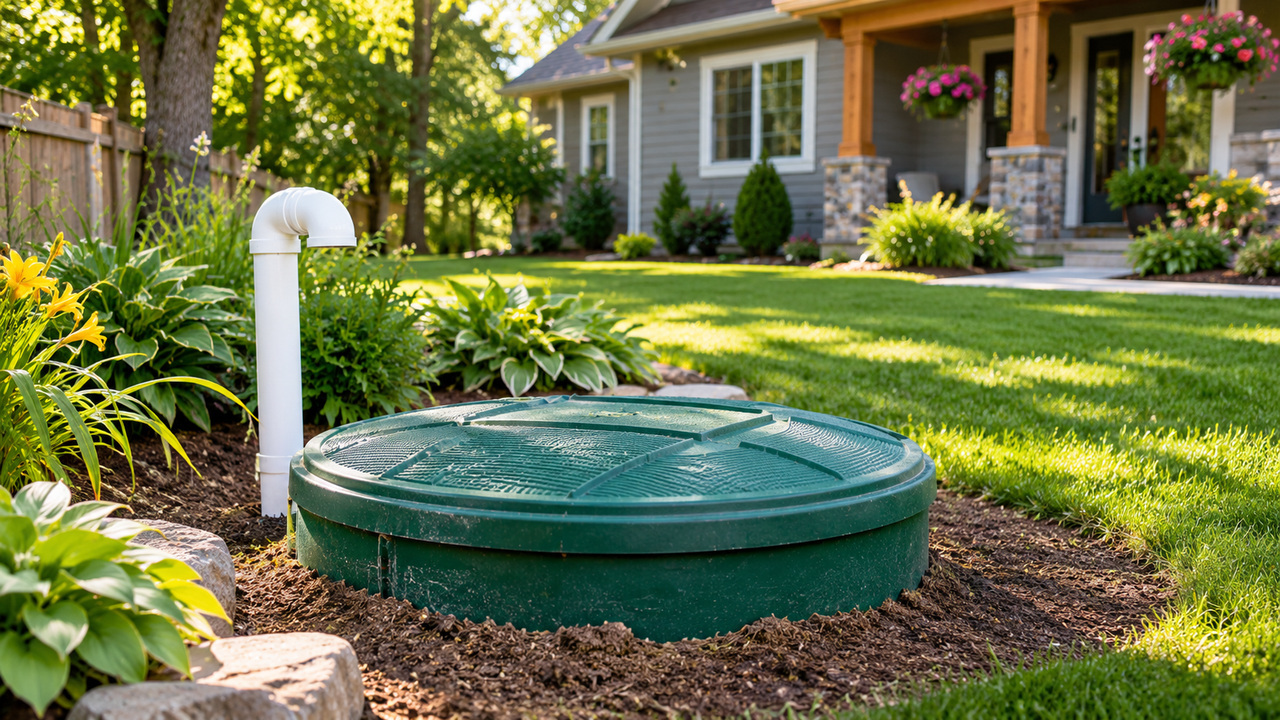
A septic system typically collects wastewater from the home, treats it in a tank, and disperses it through a drain field or another approved treatment arrangement. Unlike a public sewer connection, the homeowner is generally responsible for maintenance and repairs. Pumping schedules, household water use, soil conditions, and the age of the equipment can all influence how the system performs over time.

Why Lenders Pay Attention

Mortgage financing is secured by the property, so lenders want to know that essential systems are functional and that the home meets applicable property standards. Depending on the loan program, appraisal observations, and local regulations, a septic inspection or additional documentation may be needed. Some issues are discovered during a buyer’s independent inspection rather than the lender’s appraisal. Requirements vary, and not every home with a septic system needs the same review.

A Small Symptom Can Point to a Larger Problem

Slow drains, persistent sewage odors, wet areas near the drain field, or a history of frequent backups deserve attention. These signs do not always mean the system has failed, but they justify further investigation by a qualified professional. A replacement drain field or major system repair can be expensive and may require permits, engineering, or suitable space on the lot.

Ask About Records and Location

Before buying, request available pumping and inspection records, installation permits, and any drawings showing where the tank and drain field are located. Knowing the location matters because homeowners may be restricted from building structures, driving heavy vehicles, or planting certain trees over parts of the system. If the property has a pool, detached building, or planned addition, it is worth confirming that those improvements do not interfere with septic components.

Plan for Both Closing and Ownership

If an inspection identifies a problem, the buyer and seller may need to negotiate repairs, obtain specialist evaluations, or address a lender condition before closing. Buyers should also budget for routine pumping and eventual equipment replacement after moving in. A home warranty or standard homeowners insurance policy may not cover every septic-related expense, so review coverage carefully rather than assuming protection.

A private septic system is not a reason to reject a home automatically. Many systems operate reliably for years when properly designed and maintained. The smarter approach is to understand the system’s condition, its maintenance history, and any financing requirements before you make a long-term commitment.